‘Breathtakingly Fast’ McLaren W1, a $2.1 Million Hybrid, Sets a High Bar for Supercars

 4 min
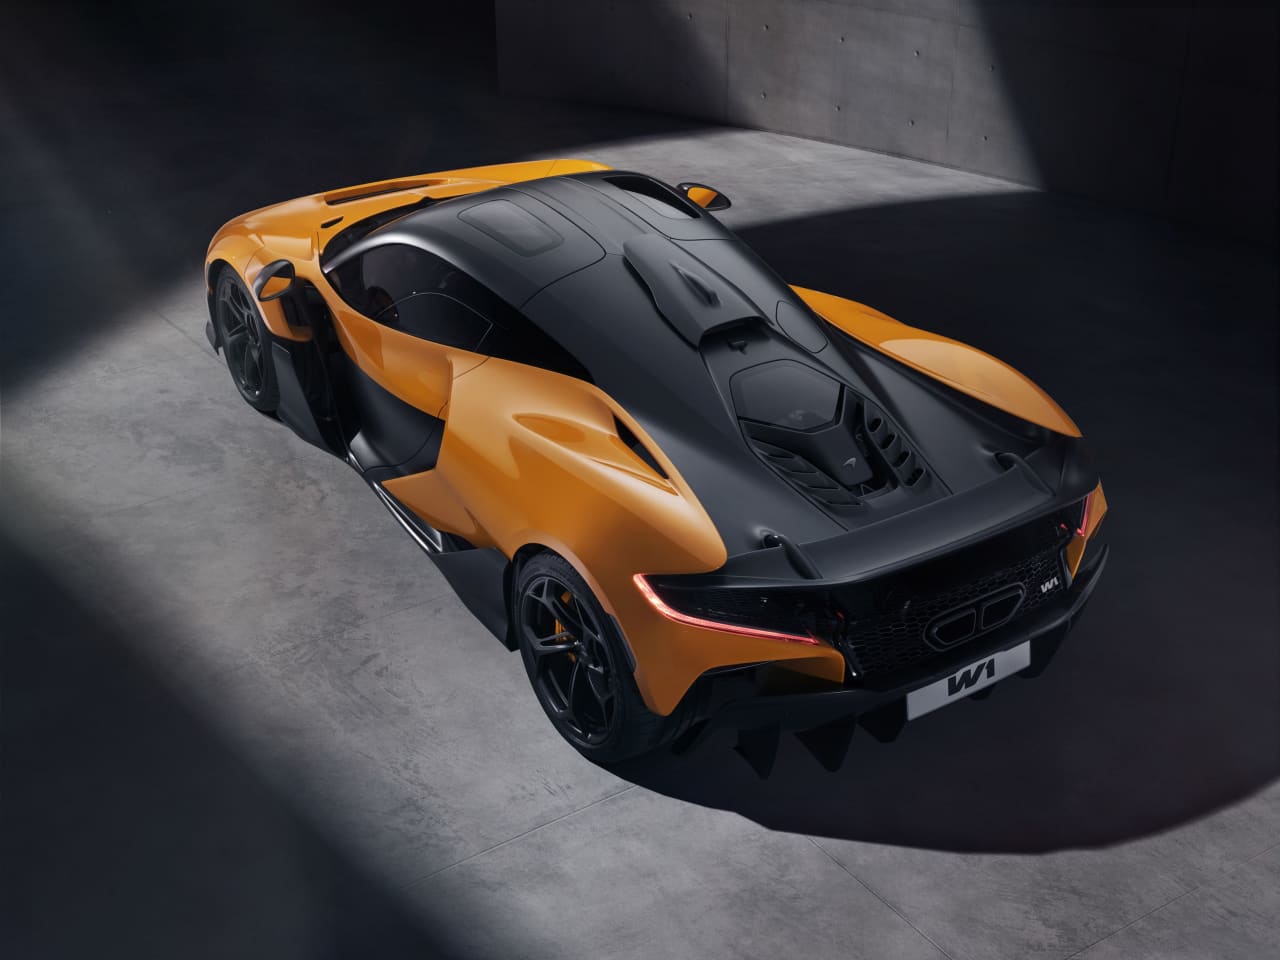
Every street McLaren since the F1 in the 1990s has been, of course, a supercar. But now the British company is hitting a new and higher mark with its W1, which has a 1,258-horsepower hybrid drivetrain—producing the most powerful McLaren to date. It’s a successor to both the F1 and the P1, and was revealed on Sunday.
Auto makers worried about the ups and downs of the battery electric car market are hedging their bets with hybrids and their plug-in variant. McLaren is no different. It has electric range, but only 1.6 miles.— he W1 will be priced at US$2.1 million, and only 399 will be sold globally. Unsurprisingly, all of them have already been allocated to customers.
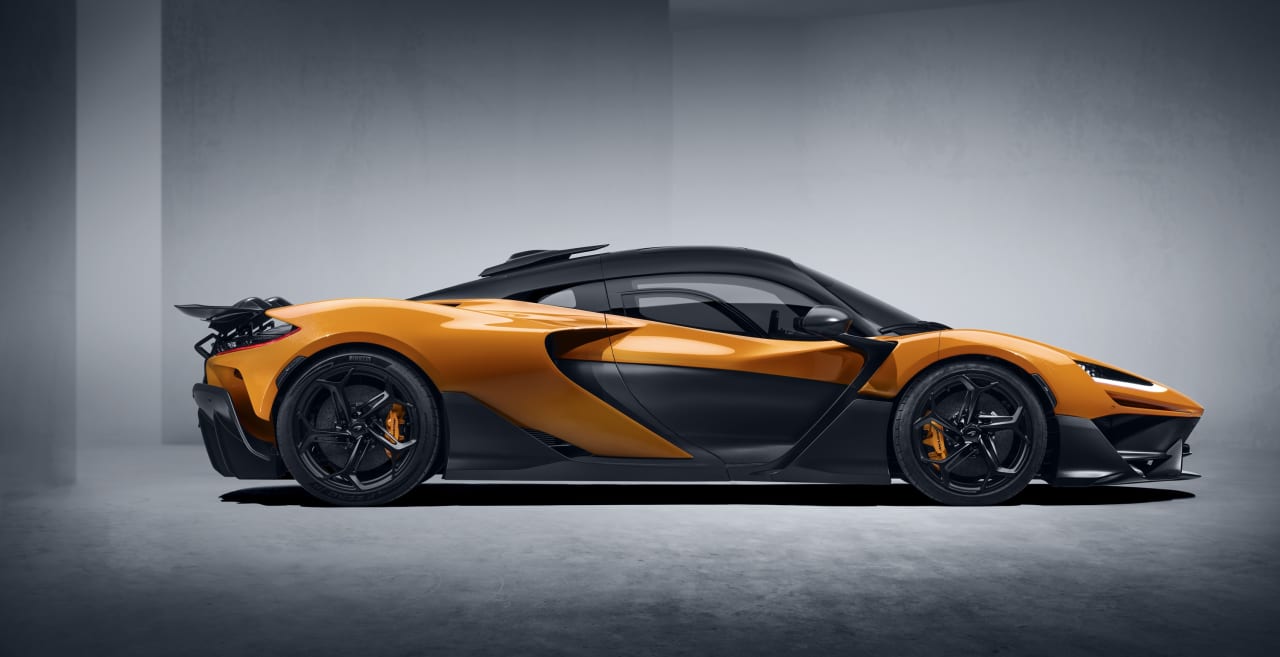
Many familiar McLaren build traditions are in place, including rear-wheel drive, lightweight carbon-fibre unit construction and uplifting gullwing-type doors hinged only at the roof. The company says the W1 doors are of “anhedral” design and optimised for aerodynamics. The doors also “allow optimisation of airflow from the front wheel arches into the high-temperature radiators, providing extra cooling space that allows the size of the radiators required to cool the powertrain to be reduced, optimising packaging and saving weight.”
McLaren
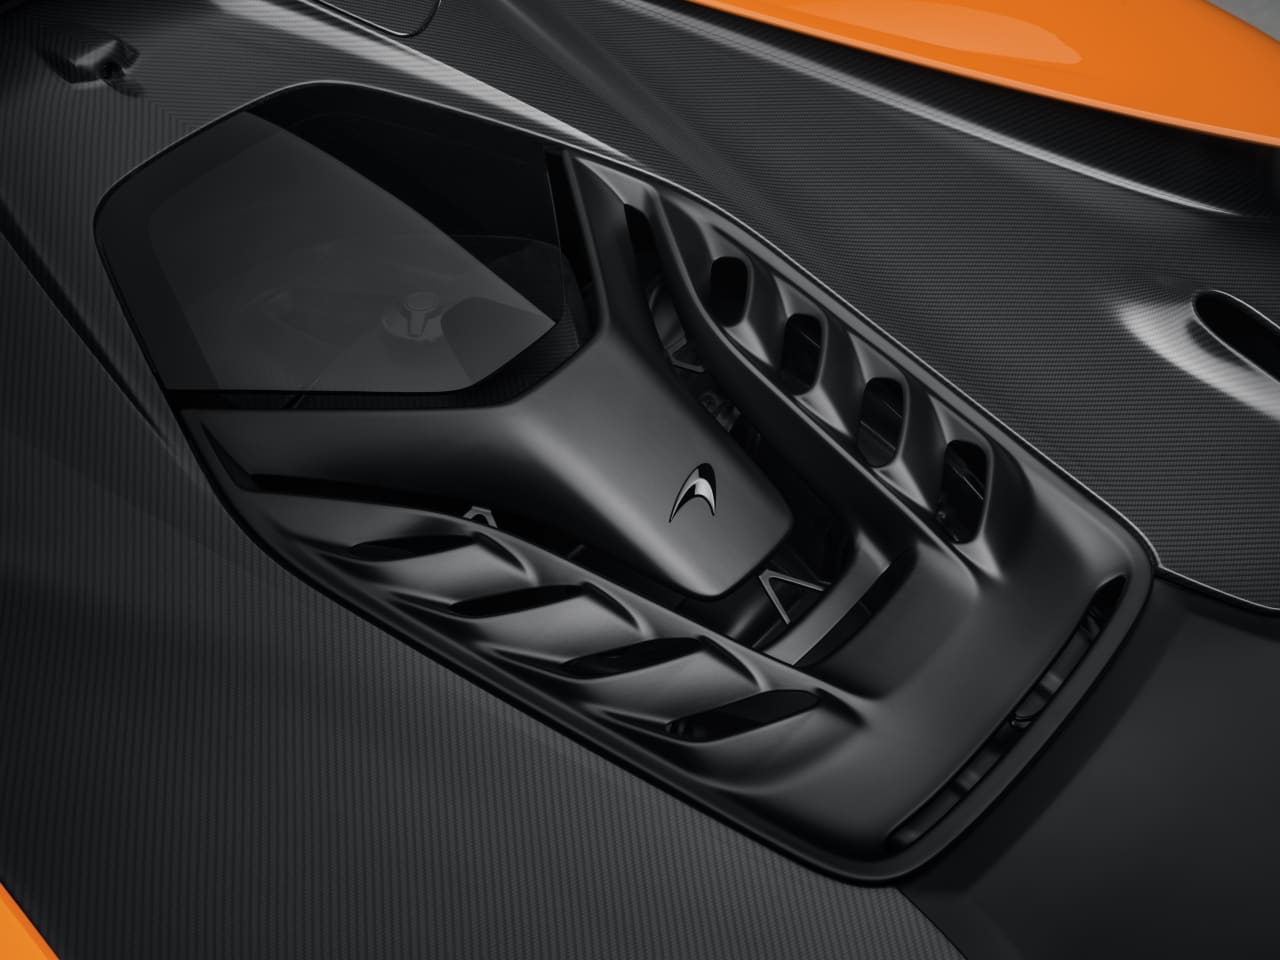
This is a breathtakingly fast car. The all-new twin-turbo, four-litre aluminium V8 engine produces 916 horsepower, and the company’s electric motor module (coupled to a 1.38-kilowatt-hour battery) adds another 342, yielding the aforementioned 1,258 horsepower and 988 pound-feet of torque. The car revs to 9,200 rpm before hitting redline, and power flows through an eight-speed transmission with electronic reverse and a technically innovative hydraulic electronic differential. In a car weighing only 3,084 pounds, this produces zero to 60 miles per hour in 2.7 seconds, zero to 124 in 5.8 seconds, and attainment of 186 mph in less than 12.7. The top speed is electronically limited to 217 mph.
The W1 is slower off the line than a US$89,990 Tesla Model S Plaid edition (1.99 seconds to 60, the company claims), but off-the-line acceleration is a big advantage of electric cars. The McLaren’s power plant is, without doubt, impressive. About that engine, Richard Jackson, chief powertrain engineer, said in a news release, “We’ve designed it to be much more power-dense than our previous V8—generating 230 horsepower per litre and capable of revving higher…with supreme driver engagement.”
The driver will have the option of choosing Race mode, which stiffens the suspension (via Race or the more bone-jarring Race+ setting) and extends downforce wings at the front and rear. The motorised wings aren’t there because they look cool—they’re capable of putting 772 pounds of downforce on the road at the front and 1,433 pounds at the back. Racing cars have to stop, so the car gets six-piston brakes up front and four-piston units in the rear. From that 124 mph, the W1 can be at a standstill in 95 feet.
McLaren
The W1 will spend a lot of its time among civilians on the road, and there’s the choice of a Comfort setting that smooths out the ride for unstressed cruising around town. Comfort uses the hybrid system only for occasional torque applications. Sport is the interim choice, with full hybrid availability and faster throttle response.
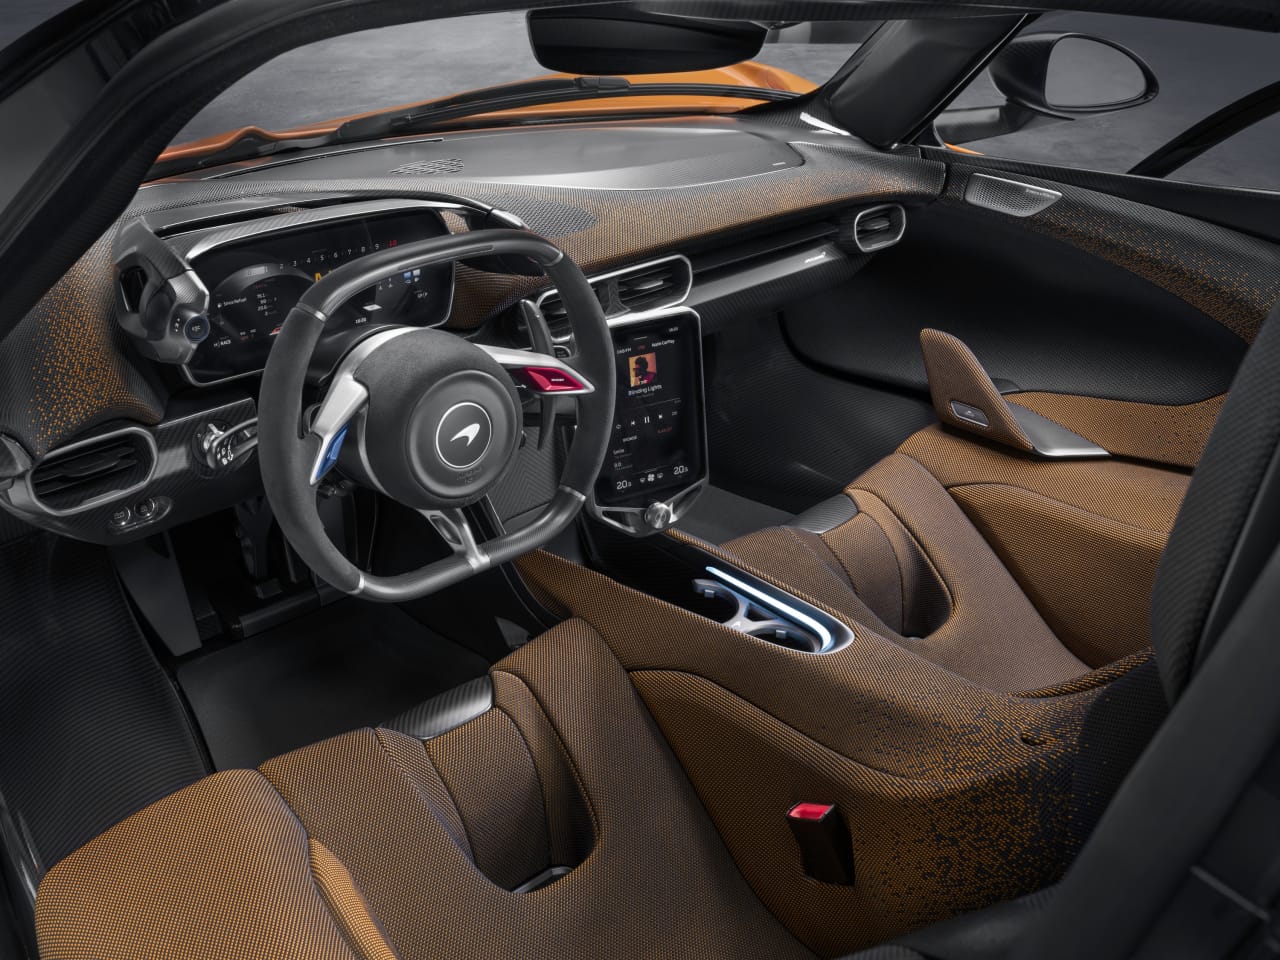
Photographs of the W1 show an exceptionally aerodynamic two-door supercar, shaped by the preferences of the wind, in a gold-and-black two-tone color scheme, with that pattern carried over into the seating. The bottom cushions are gold but the black gradually intrudes in what might be called a Jackson Pollock thrown-paint effect. The mid-mounted engine, just behind the driver, is part of the design.
McLaren
In keeping with the trend toward owner customisation, McLaren says there are “virtually unlimited bespoke options” for the W1, including a new lightweight knitted-to-fit interior material called InnoKnit. The company claims that visibility is “best in class,” which is good if it means the driver can actually see what’s happening behind the supercar—a notorious issue. The driving position is said to be fairly reclined, with plenty of thigh support—useful when these cars corner at high speeds. The aluminium pedals are adjustable.
Start/stop buttons, the gear selector, window controls, and Race-mode switch are all mounted overhead the driver, with the Boost button on the steering wheel. The 8-inch centre screen offers USB-A and -C, as well as Apple CarPlay. Supercars aren’t known for storage space, but the W1 has small stowage and a sliding cup holder between driver and passenger. Weekend bags (or crash helmets) can be stashed behind the seats if the headrests are moved aside.
The W1’s fuel economy will undoubtedly be helped by its hybrid drive, but an actual figure has yet to be announced. It wasn’t a make-or-break figure for customers in this league.
Even aficionados of the marque who already own a McLaren Senna will want a W1, because it has 102 horsepower more. Keep in mind that 102 horsepower was considered perfectly adequate for British sports cars of the 1950s. In that same era, racers would drive to the track, compete, and then drive home again. The W1 appears ready to bring back that era.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”

Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”
2 min
A property portfolio can look comfortable until several small pressures arrive together: a rate increase, a vacancy, higher insurance and an unexpected repair. The correct time to model that combination is before it occurs.
Start by recalculating every loan at 0.25, 0.50 and one percentage point above its current rate. Include principal-and-interest repayments even where a loan is temporarily interest-only, because the eventual step-up may be larger than the next RBA move.
Then calculate true net rent. Deduct management, council and water charges, strata, insurance, maintenance, land tax where applicable and a vacancy allowance. A property advertised with an attractive gross yield can produce a very different result after these costs.
Third, review the portfolio’s liquidity. An offset account can reduce interest while keeping cash accessible, but investors should obtain tax advice before moving funds between loans. The distinction between investment and private debt affects deductibility, and poorly structured redraws can create lasting complexity.
Fourth, examine refinancing risk rather than just today’s rate. A highly leveraged investor may be unable to refinance on the same terms because the new lender tests total debt at a higher assessment rate. Credit-card limits, owner-occupied debt and shaded rental income can all reduce capacity.
Fifth, rank properties by resilience. Consider net yield, vacancy risk, near-term capital expenditure, tenant demand, debt attached and the cost of selling. This is not an instruction to sell the weakest performer automatically; transaction costs and tax consequences matter. It is a way to identify where pressure would emerge first.
Investors should also review fixed-rate and interest-only expiry dates. A portfolio with several facilities resetting in the same quarter carries concentration risk even when each loan appears manageable individually.
The goal is not to predict the RBA perfectly. It is to ensure that one policy decision does not force a rushed refinancing, sale or reduction in essential maintenance. A portfolio that can absorb higher rates and temporary income interruptions gives its owner time to make deliberate decisions.
Read more: What mortgage holders should do before the next RBA decision
Portfolio checklist
Stress test: Current rate plus 0.25, 0.50 and one percentage point.
Model: Net rent after every recurring cost and vacancy.
Check: Fixed-rate expiries, interest-only expiries and loan maturity.
Preserve: An accessible emergency buffer.
Review: Insurance, land tax, strata works and major maintenance.
Seek advice: Licensed credit, financial and tax advice before restructuring.

Two coming 2027 models – the first of the “Neue Klasse” cars coming to the U.S. early next year – have been revealed.

An opulent Ryde home, packed with cinema, pool, sauna and more, is hitting the auction block with a $1 reserve.